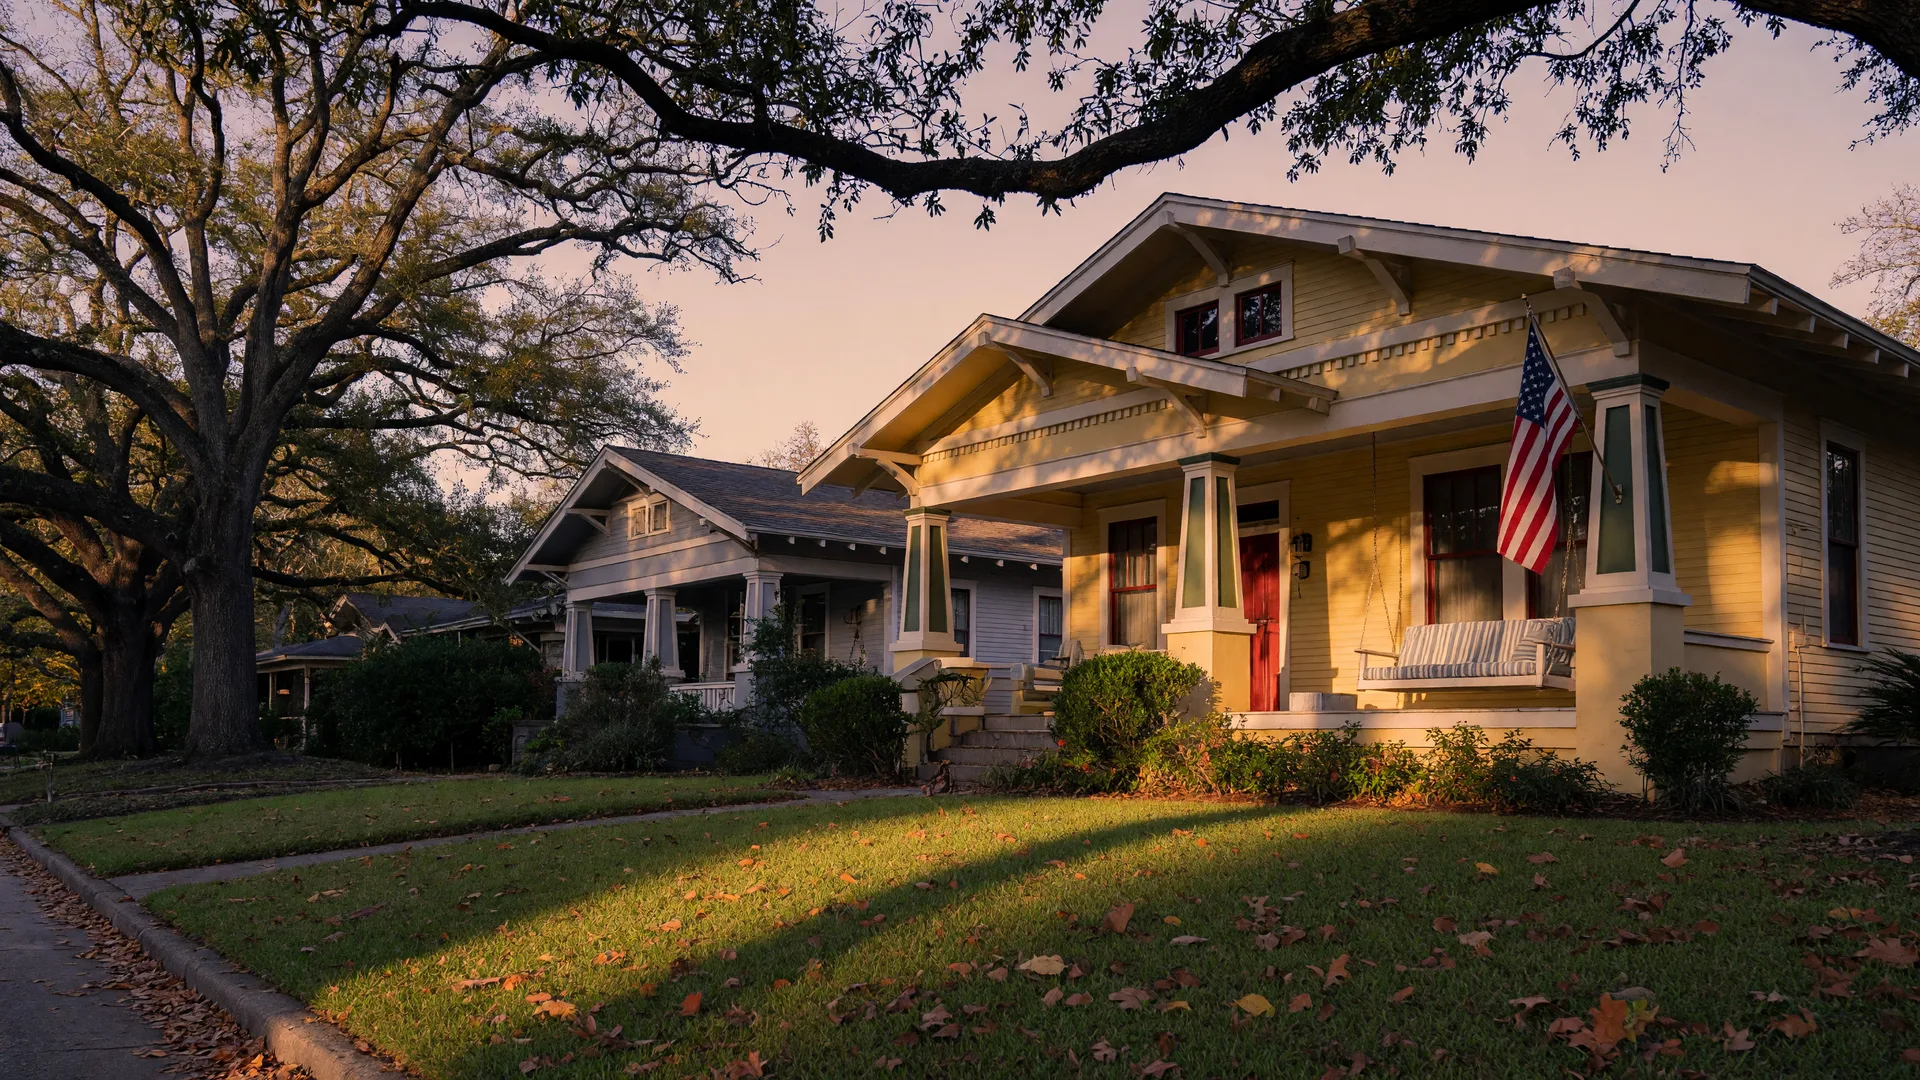
VA loans let eligible veterans, active-duty service members, reservists, and certain surviving spouses buy a home in Houston Heights, Garden Oaks, Oak Forest, Timbergrove, Montrose, or Spring Branch with no down payment and no monthly mortgage insurance. Since 2020 there has been no county loan limit for borrowers with full entitlement, so the benefit works whether you are buying a first ranch in Oak Forest or a luxury bungalow in the Heights. Here is how it works in 2026, what Texas adds, and how it fits today's market.
The VA Loan Basics: Zero Down, No PMI
Three features set a VA loan apart. Qualified buyers put no money down, pay no private mortgage insurance premium, and benefit from a government guarantee that lets lenders offer competitive rates with flexible credit standards. In exchange there is a one-time VA funding fee, and it can be rolled into the loan instead of paid at closing. Veterans who receive VA disability compensation, along with certain surviving spouses, are exempt from the fee entirely. You can also use the benefit more than once: entitlement is restored when an earlier VA loan is paid in full, so it can serve later purchases too.
The 2026 Funding Fee in Plain Numbers
The funding fee is a percentage of the loan amount, and the rates are unchanged from the schedule that took effect in 2023. On a first-time use, you pay 2.15% when putting less than 5% down, 1.5% with 5% down, and 1.25% with 10% down; subsequent-use purchases run 3.3% under 5% down. On a $750,000 purchase with zero down, the fee is roughly $16,100, and it is financed into the loan so you are not writing a separate check at closing. If you receive VA disability compensation, tell your lender before they quote costs, because the exemption changes the math.
What the Loan Covers in the Heights and Inner Loop
The county loan limit that once capped VA lending effectively disappeared on January 1, 2020 for borrowers with full entitlement, which is why VA financing can wrap around homes well above $1 million in the Heights. Partial-entitlement borrowers still see a ceiling: the 2026 conforming loan limit baseline is $832,750 for a one-unit property, and Texas counties generally sit at that number. Your Certificate of Eligibility spells out which category you are in. The reach matters here: Greater Heights market data put the median sold price near $861,000 in September 2026, with about 4.8 months of inventory, so competition is real but more balanced than a few years ago, and a well-prepared VA offer is a legitimate player.
What Texas Adds on Top
Texas is one of the most veteran-friendly states for home buyers. The Texas Veterans Land Board's Veterans Housing Assistance Program raised its home-loan cap to $832,750 for 2026 and offers fixed-rate 15, 20, 25, and 30 year loans to eligible Texas veterans, active-duty, and Guard and Reserve members, with discounted rates for a 30% or higher service-connected disability rating. The property tax side is strong too: a 100% service-connected disability rating earns a full homestead exemption on your primary residence, and ratings between 10% and 99% reduce taxable value by roughly $5,000 to $12,000. Add the appraisal cap a Texas homestead filing locks in, and the monthly cost looks better every year. Our property tax and homestead guide walks through the paperwork.
Using the Benefit Well in These Neighborhoods
Active-duty buyers can count Basic Allowance for Housing as qualifying income, which often tips the numbers in pricier pockets like Woodland Heights or the Rice Military townhome corridor. Historic districts are no obstacle: a VA appraisal simply verifies value and condition, and our guide to buying a historic Heights home explains how that process unfolds. The practical first step is the same for every buyer: get pre-approved early, review your Certificate of Eligibility, and set your budget before you tour. Our mortgage pre-approval guide lists the documents lenders want most.
"With us, you're not a number but a neighbor."
Shawn Manderscheid, The Shawn Manderscheid Team
A Team That Knows the Loan and the Neighborhood
The Shawn Manderscheid Team has helped Houston-area families buy and sell in these neighborhoods for more than 25 years, and our family roots in the Heights go back four generations. We work with experienced VA mortgage specialists, know which local lenders move quickly on government loans, and have represented veterans in plenty of competitive situations. Whether you are shopping Garden Oaks for your first home or a luxury Heights property after a move, we will make sure your benefit works as hard as you did to earn it. Reach out anytime for a no-pressure conversation, or start with our Inner Loop neighborhood guides to see where your VA loan fits best.